
Flood Performance Certificates enter pilot alongside new resources platform

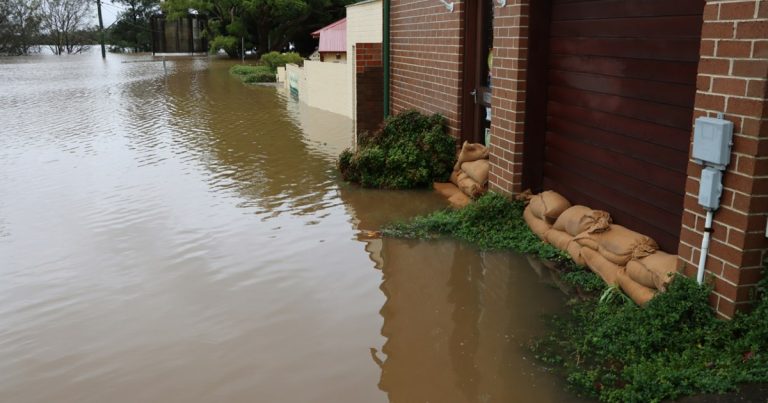
Flood risk has been one of the harder conversations in conveyancing. A search result can tell a buyer that a property sits in a flood zone, or that surface water risk is elevated, but it rarely tells them what that means for the building in front of them. A Flood Performance Certificate aims to close that gap, and a pilot is now underway alongside a new resources platform for property professionals and homeowners.
What a Flood Performance Certificate is trying to do
The concept borrows its logic from the Energy Performance Certificate. Rather than describing the hazard at a postcode or polygon level, the certificate assesses the individual property: how exposed it is, how it would perform if water reached it, and what resilience measures are already in place or could be installed. The output is intended to be a property-specific picture rather than a probability band.
That distinction matters. Two houses on the same street can face very different outcomes from the same event, depending on floor levels, construction, door and air-brick protection, drainage and whether previous flooding prompted resilient repairs. Standard flood data cannot see any of that. A performance-based assessment can.
Why this is a conveyancing issue, not just a surveying one
Conveyancers are the point in the transaction where flood risk becomes a documented matter. The Law Society's guidance already expects the issue to be raised, environmental and flood searches are routinely ordered, and the TA6 form asks sellers about past flooding. The practical difficulty has always been the next step: once a report flags elevated risk, what does the firm actually advise?
Current options are limited. You can recommend a specialist flood report, suggest the buyer speaks to an insurer, confirm Flood Re eligibility where relevant, or advise a survey. None of these produce a single, comparable document that a lender, insurer and buyer can all read the same way. A certificate format, if it gains traction, could become that document.
The likely impact on search ordering
If the pilot develops into a wider rollout, a few things change in day-to-day practice.
Triage becomes more important. A certificate is unlikely to be ordered on every transaction. The sensible model is a screening search that identifies elevated risk, followed by a certificate where the result warrants it. That makes the quality and interpretation of the initial environmental or flood search more consequential, not less.
Advice becomes more specific. Where a certificate exists, the file note changes from "buyer advised of flood risk and recommended to check insurance" to a discussion of named resilience measures and their effect. That is better for the client and better for the firm's risk position.
Lender and insurer expectations may follow. EPCs became embedded because they were required, not because they were popular. If lenders or insurers begin to reference flood performance information, the certificate will stop being optional and start being a step in the process. Firms that have already worked out how they order, store and explain these documents will have less to rebuild.
Reasonable caution
A pilot is a pilot. Questions remain about cost, who commissions the assessment, turnaround times, assessor competence and how the output interacts with existing search products. There is also a risk of duplication, with buyers paying for overlapping information across a flood search, a survey and a certificate. Those issues tend to be resolved by market practice rather than announcement, and it will take time.
There is also the seller-side question. An EPC is the seller's obligation. If flood performance information ever moves in that direction, it changes listing preparation and the information pack conveyancers receive at instruction.
What firms can do now
Nothing in the pilot requires immediate action, but it is worth reviewing how your firm currently handles a positive flood result. Is the advice consistent across fee earners? Is it recorded clearly? Do you have a standard escalation route when a search flags risk? Those processes will carry over regardless of what shape the certificate takes.
The underlying direction is clear enough: flood risk reporting is moving from hazard mapping toward property-level assessment, and conveyancers will be the ones explaining the difference to buyers.
See how Searchpoint can streamline your environmental and flood search ordering – try it today.